Nice steady salary on the first of every month? Then the 50-30-20 rule is easy: half for needs, a third for wants, a fifth into savings. Sorted. But say your income doesn’t work like that. A fat month, then a thin one, then who knows. Now the rule gets awkward, because fifty percent of what, exactly? The good news is it still works for you. It just needs one adjustment to cope with an income that won’t sit still.
Table of Contents
Which income figure do you even take 50% of?
Not whatever happens to land this month. Pick a steady base to budget against, your reliable floor or a cautious average, and split that. Cover your needs from it first, keep your wants in check, and when a fat month turns up, push the extra straight into savings rather than into your lifestyle.
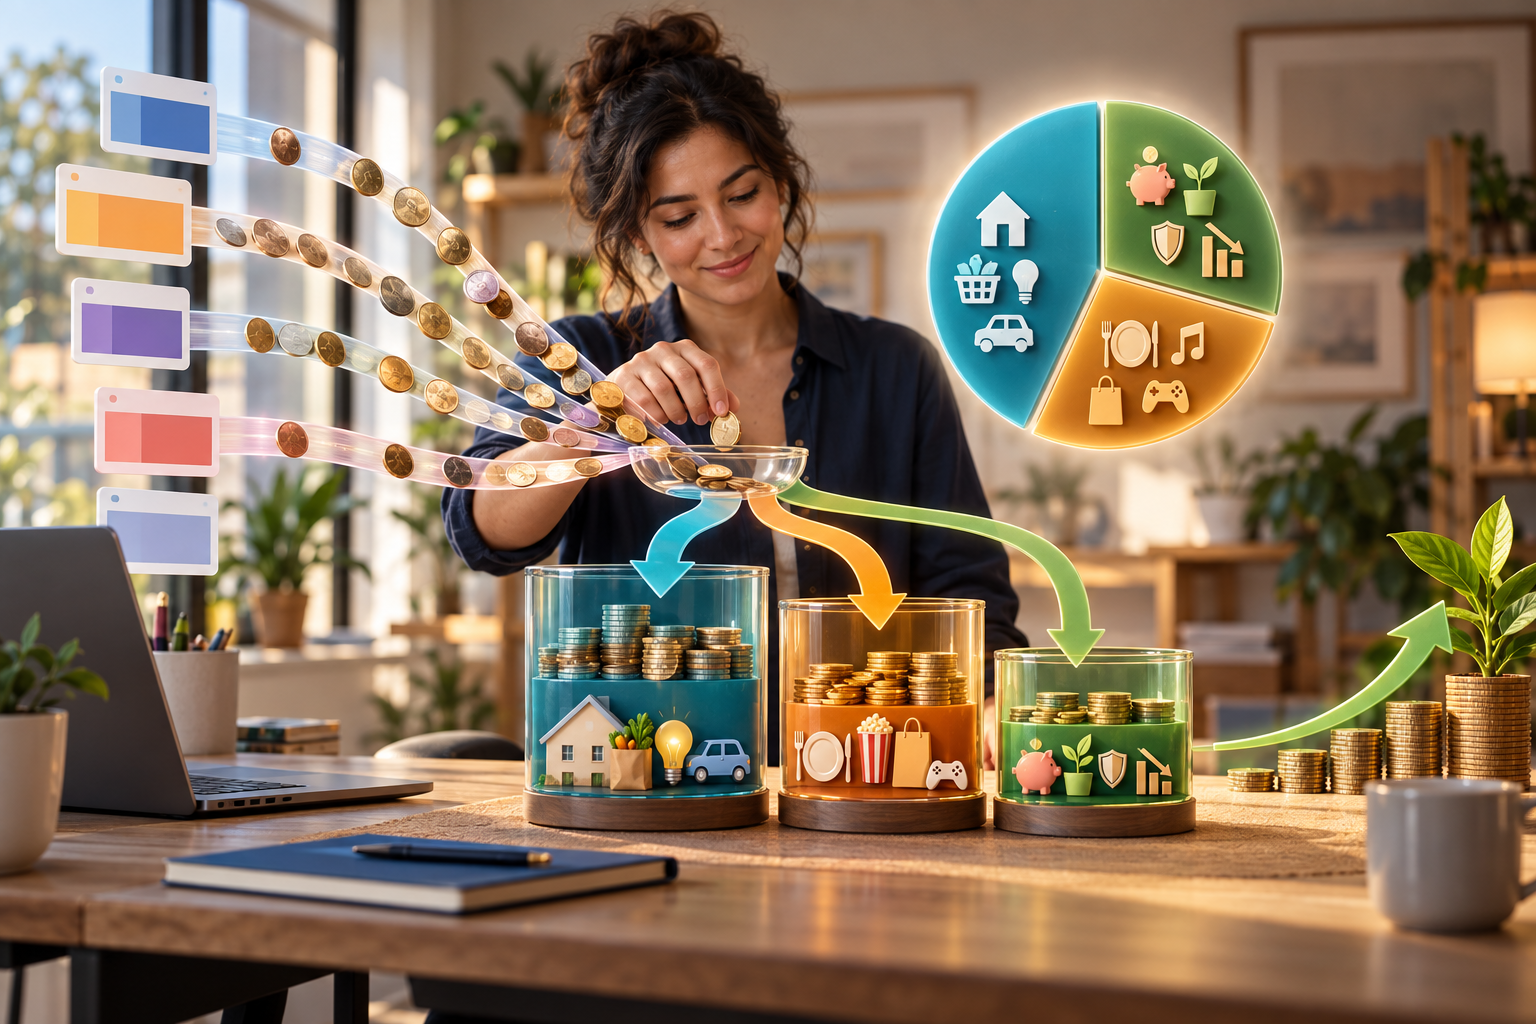
The 50 30 20 rule itself doesn’t change: roughly half your money to needs, a third to wants, a fifth to saving. What changes for a variable earner is the number you apply it to, and how you treat the months that overshoot.
Why doesn’t the standard rule fit a variable income?
Because it quietly assumes the same figure every month, and yours isn’t. Your rent, food, and bills stay roughly the same in rupees whether you earned a lot or a little, so a fixed percentage of a shrinking income can leave your needs underfunded.
Twenty percent of a strong month and twenty percent of a weak one are very different amounts. If you only save when there’s plenty left over, you’ll save next to nothing in the lean stretches. The rule needs a steadier anchor than this month’s total.
What number should you actually budget against?
Your reliable floor, not your hopeful average. Look back over the last several months, find the income you can count on even in a slow one, and build your 50-30-20 around that.
If a strict floor feels too tight, a conservative average works too: add up a year of income, divide by twelve, then shave it down a little for safety. Either way, you’re budgeting against a number you’ll actually hit most months, so the plan doesn’t collapse the moment work dries up for a while.
Does it have to be exactly 50-30-20?
No, the numbers are a starting point, not a law. If your essentials eat more than half your income, a 60-20-20 split is more honest than pretending needs squeeze into 50. If you’re keen to save faster and your wants are light, you might flip to 50-20-30.
The spirit matters more than the exact figures: cover what you must, enjoy a bit of it, and pay your future self a fixed slice. For a variable earner especially, a split you can actually stick to beats a textbook one you keep breaking.
How do you handle the good months and the lean ones?
When a good month lands, don’t blow the surplus. That’s the money that has to carry you through the slow ones, so push it into savings and a buffer instead of letting your spending creep up to match.
In lean months, your wants take the hit first. Trim the 30% before you touch needs or raid savings, and lean on the buffer you built when times were good. Done right, the buffer does the smoothing, and your month-to-month budget barely feels the swing.
Can you pay yourself a steady salary?
This is the trick that makes the whole thing work. Instead of spending whatever arrives, pool your income in one account and pay yourself a fixed amount each month, like a salary you set yourself.
You bank the highs, draw a steady figure, and top up from the pool when a month falls short. Then you apply 50-30-20 to that steady salary, not to the chaos underneath it. It turns an unpredictable income into a predictable one, which is exactly the situation the rule was built for.
Where should the 20% actually go?
Somewhere it isn’t easy to spend by accident. The saving portion does far more when it’s parked with a purpose rather than left sitting in your spending account.
Part of it belongs in an emergency fund until that’s solid. After that, steady saving schemes can hold the longer-term money, and a growth option can take whatever you’re happy to leave untouched for years. For a variable earner, keeping some of it within reach matters more than usual, since your buffer and your savings are doing related jobs.
What should you protect no matter the month?
A short list that never flexes. Your needs, your emergency fund top-ups when you can manage them, and any insurance premiums come before wants, every single month.
These are the non-negotiables that keep a bad month from turning into a crisis. Wants can wait, and savings can occasionally pause in a genuinely awful stretch, but the essentials and your cover shouldn’t. Protect those first, and the rest of the rule has room to flex around them.
How do you keep it simple month to month?
The less you have to think about it, the more likely you are to stick with it. Separate accounts help: one for the income pool, one for spending, one for savings, so the money is sorted before you’re tempted by it.
Set your self-paid salary to move on a fixed date, and let the savings transfer happen automatically the moment it lands. Then check in every few months rather than every day, nudging your floor figure up or down as your income picture shifts. A simple setup is the one you’ll still be running when things get hectic. Anything fiddly tends to get quietly dropped.
The bottom line
The 50-30-20 rule survives a changing income; it just needs a steady number to work from. Budget against your floor or a cautious average, protect your needs first, and save hard in the good months so the lean ones don’t sting. Pay yourself a level salary from a pool if you can, and apply the split to that. The percentages were never the hard bit. Getting a steady number to run them against is where this actually lives or dies.
This is general budgeting guidance rather than personalised financial advice, and the right split depends on your own circumstances. Where you put your savings carries its own terms and risks, so check the details and conside r speaking to an adviser before you commit.